The Price of (Un)Certainty (Full Paper here – 50 pages)
The Price of (Un)Certainty (Summary Paper here – about 10 pages)
When TIPS yields breached near all-time highs this past Summer I figured it was time to start seriously considering the utility of TIPS in a portfolio. I’ve never loved matching long duration bonds with long duration liabilities because bonds are riskier than many assume in the long-run and equities, while risky, provide so much asymmetric upside that they are typically much better suited for long durations. But the math starts to shift with real yields at 2.5-3% across the curve and equity valuations at record highs. So I decided to price the cost of certainty across the asset spectrum because, even though a 30 year TIPS is highly certain, it has an enormous potential cost in its opportunity cost compared to instruments like equities. This paper does a deep dive into the price of (un)certainty across the spectrum or time and assets.
I am tempted to say this is the single most important thing I have ever written (low bar, don’t remind me). It ended up being 50 pages, which I decided was at least 40 pages too much, which is why the summary exists. I am not oblivious to the reality that no one wants to read 50 pages of ALM research from me. But this is also exciting for me as I feel like I am finally beginning to get to a point where I have distilled this entire framework down into a relatively simple and easily implementable process that begins with the financial planning and dumps out the matching assets in a highly systematic methodology. It is truly liability driven, diversified, planning based, low cost and behaviorally robust.
Anyhow, what this paper does is explain this particular multi-asset ALM framework, why it’s potentially superior for households and then quantifies the price of uncertainty across all different instruments including TBills, TIPS, nominal bonds and equities to provide a real-time view of the trade-offs an investor must consider in an environment where every asset is both expensive in certain ways and cheap in others.
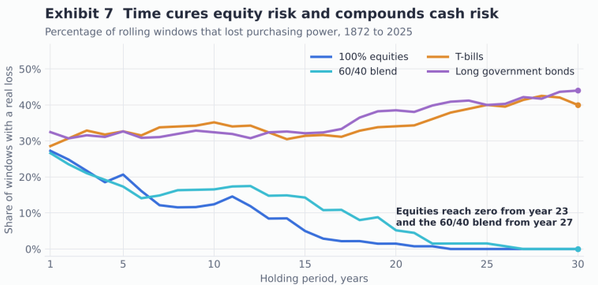
Exhibit 7 in the summary shows the price of (un)certainty across different instruments. In real terms, cash and bonds are more certain in the very short-term, but become riskier the longer you hold them. Inflation compounds with time and hurts bonds while equities are riskier in the short-term (both in probability of loss and magnitude) and become less risky in real terms with time.
But the mix you arrive at shouldn’t be determined by emotions, styles, factors, efficient frontiers or active management. The mix should be liability driven and it should be derived by how much money you need and at what time in your life. That is, after all, what financial risk tolerance really is – how certain are you about the quantity of money you need to consume the things you need/want in life. Your risk capacity should determine your asset mix and that is entirely a function of the health of your income statement vs the balance sheet. Someone who is 55 years old with $2MM saved and $50K net income has a vastly different capacity to take risk than the investor who is 55 with $500K and the same $50K net income. Investor A can take more risk purely as a function of their liability needs across the future. And the higher the risk capacity the more equity risk the investor can take across time. These investors might answer a risk tolerance questionnaire with completely different responses and the investor who lets their emotions dictate portfolio outcomes will overpay for certainty all along the way thereby deteriorating their ability to meet their financial goals. It is the role of a good financial advisor to show the investor that their risk capacity guides sound probabilistic asset allocation while bounding emotions in certainty that can be shown through quantifiable methodologies and not hope.
This is an important enhancement in ALM strategies because, as we show, blended instruments like a 60/40 stock/bond portfolio are not merely diversified multi-asset instruments that sit somewhere on an efficient frontier. They are, very specifically, a temporal construct that can operate much like a longer duration bond with the potential for equity risk premia when held over an appropriate time horizon. This multi-asset approach fills an important gap in traditional ALM processes by potentially enhancing the way an investor can plan for the intermediate and long time horizons that bonds often fail to protect investors from.
This is where the framework becomes very useful for households and institutions who rely too heavily on bond-only ALM processes. This paper specifically differentiates between the old way of doing ALM (contractual fixed income only ALM) and the new way of doing it (applying statistical analysis of instruments like equities and multi-asset instruments). This allows the ALM investor to apply a blended version where an investor with a high risk capacity can take a more statistical approach while the investor with a greater need for certainty requires more contractual guarantees. Importantly, I don’t argue for or against any instrument mentioned here. They are all decent tools for different jobs.
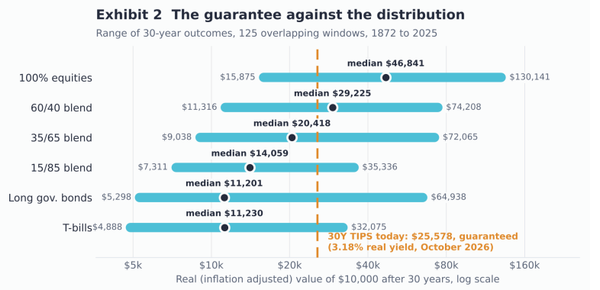
Exhibit 2 probably best summarizes the conclusions of the research and how an investor has to consider different trade-offs across time in different instruments. We take the current 30 year TIPS yield and compare it across the curve of instruments to show how different durations and asset mixes provide (un)certainty.
The full paper goes much deeper than that. Much, much deeper. But I don’t expect most of you to read that because, as the paper emphasizes, time is our most important asset and 50 pages takes a long time to write, let alone read!
And here I am rambling again. Apologies.
In short, TBills and short duration nominals remain extremely attractive. For the investor with a lower risk capacity, TIPS, at current real yields of 2.5-3%, should be a serious consideration as far out as 15-20 years. For the investor with a higher risk capacity blended instruments still provide an intriguing potential upside due to potential for more equity risk premia. And for the truly patient and long-term investor, even at near record high valuations, global equities still provide the certainty that almost no other instrument can match. And perhaps most importantly, diversifying your equity holdings, both globally and domestically, might be the most important piece of the puzzle here as the AI trade continues to be the most uncertain short-term outcome of them all.
I hope you enjoy this and that it challenges some of the conventional thinking out there. Most importantly, I hope it provides you with some certainty in a world filled with uncertainty. As always, thanks for your interest in my work and remember to stay disciplined out there.